
Waterhouse VC invests globally in publicly listed and private companies across the wagering and gaming ecosystem. The Fund is available to wholesale investors only.
Since inception (August 2019), Waterhouse VC has achieved a net total return of +2,792% (60.5% p.a. annualised) as at 30 September 2026, assuming reinvestment of all distributions on 1 July each year. Past performance is not a reliable indicator of future performance
Licence to Print
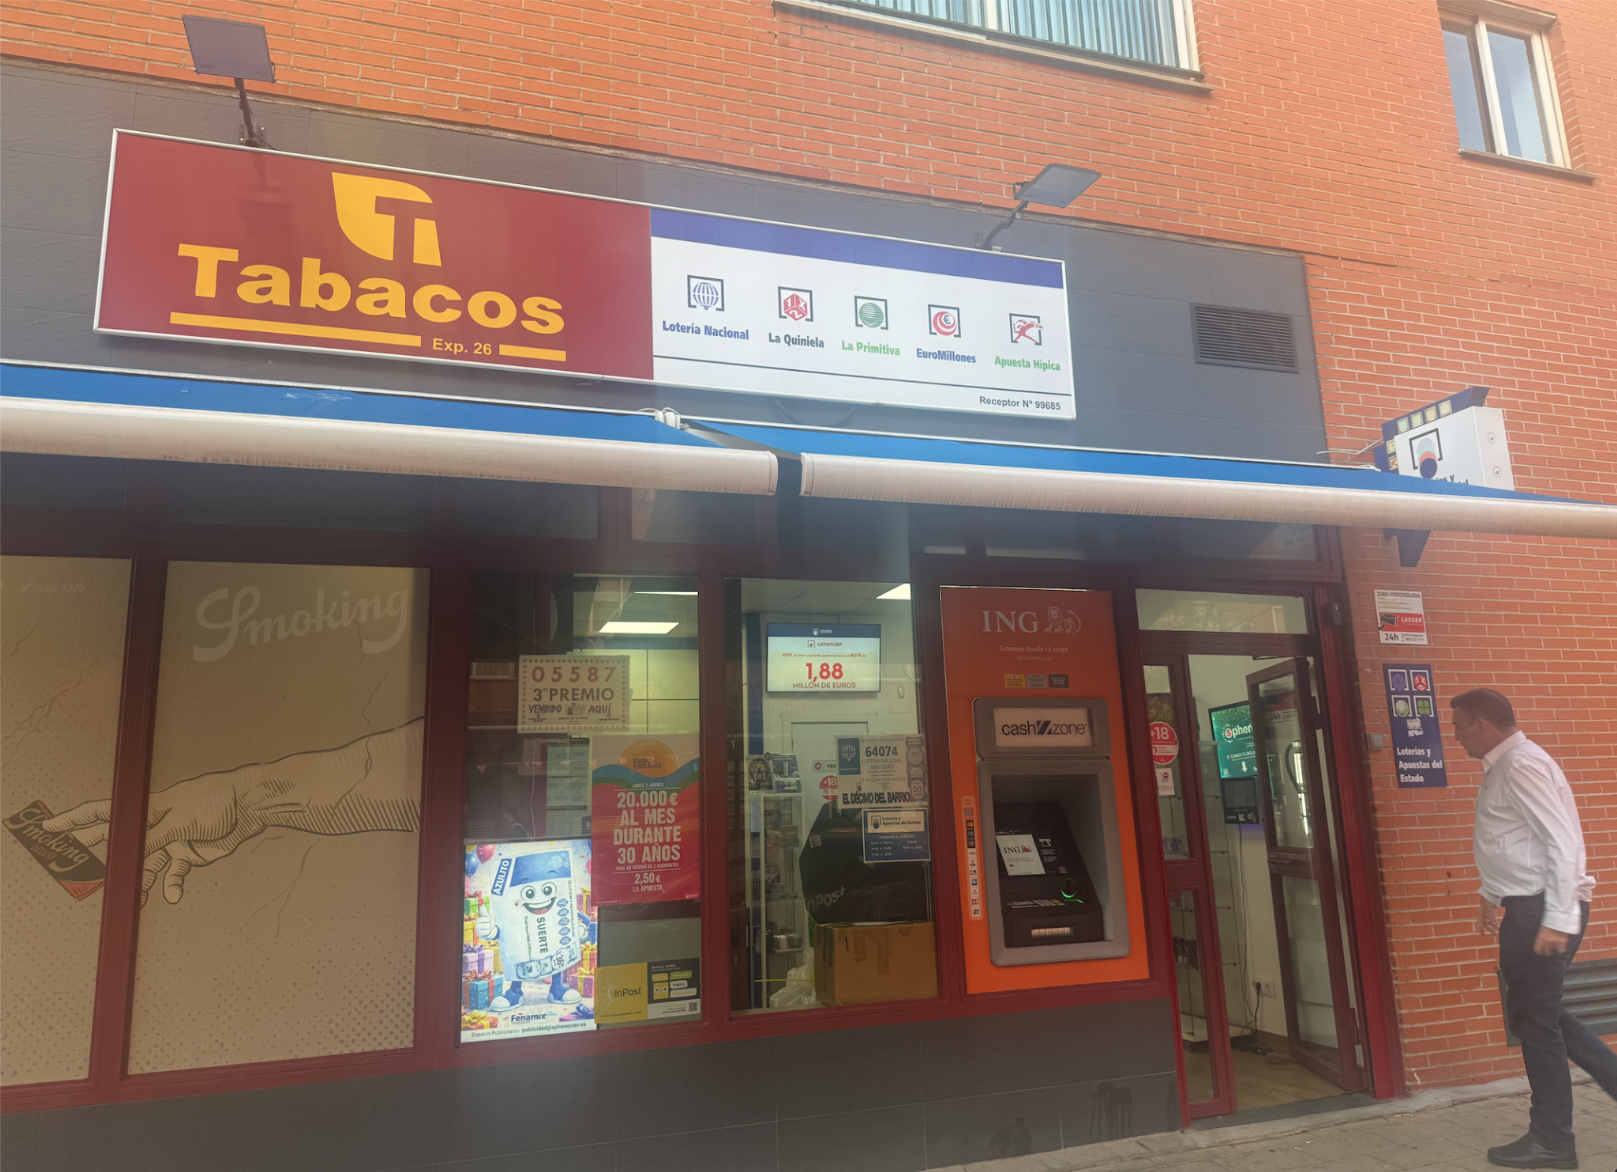
One of the world's largest lottery markets runs through Spain's neighbourhood shops. In October, Waterhouse VC visited three of them in Madrid, where lottery tickets shared the counter with tobacco and parcels. One owner showed us a printout recording around 1,300 lottery transactions that morning.
Spain’s state operator SELAE sold €10.6bn of tickets in 2025, but less than 3% came through its own website and app. The rest was attributed to its 10,867 authorised retailers, including orders those shops received online. Digital growth can still run through the neighbourhood counter.
We came back convinced these shops have a lasting role. For Waterhouse VC, the opportunity lies in technology suppliers that earn recurring revenue by making those shops more profitable.
SELAE paid its retailers €775m in commissions in 2025. Retailers typically earn 4.5% to 6% commission depending on the game, so technology must pay for itself through extra earnings or time saved.
Lottery, tobacco, an ATM and parcel services at one address. Madrid, October 2026
An Established Habit
Spain’s Christmas draw, best known for its top prize El Gordo, sold €3.55bn of tickets in 2025, a third of SELAE’s annual sales. Each €200 ticket is split into ten €20 décimos, allowing friends, families and colleagues to share a number. Nobody wants to opt out when the office syndicate wins.
At the mixed outlets we visited, owners knew their regulars, who bought tickets and checked results while buying cigarettes or collecting parcels. New services could reach customers through a shop they already trust.
Counter Productive
For a mixed retailer, lottery competes for attention with everything else happening at the counter. Easier ordering, automatic sales records and self-service ticket checking could reduce the work of serving each customer.
Syndicates can bring shops additional sales, but also more administration. Known as peñas, these groups pool money for regular draws and share any winnings. Someone must track contributions and each member’s entitlement; Spain’s consumer organisation OCU advises keeping written records of ownership.
Two owners told us they avoid offering syndicates because of the paperwork. Software that automates parts of the process exists, but feedback relayed to us suggests it still leaves too much of the organising and record keeping with the retailer. A subscription is hard to justify if the shopkeeper still does most of the work.
Letting customers create and organise their own groups could lighten the retailer’s workload. Software would keep the participation records, while an authorised retailer issued the tickets and earned its normal commission. The shop could serve groups it had neither recruited nor organised.
Australia shows how retailers can share in digital growth. The Lottery Corporation launched online store syndicates in 2022, paying the same commission as counter sales. By February 2026, around 80% of its retailers were selling syndicate shares through the platform. Those groups are retailer-created, but the lesson holds: shops need a financial reason to participate.
The same applies to ordinary ticket orders. Moving an existing sale online is not automatically extra income, but online ordering can reach younger customers who are less frequent at the counter, provided the shop still records the sale and earns the commission.
Opening the Network
FENAMIX, the national federation of more than 6,500 mixed lottery outlets like the ones we visited, offers suppliers a route into this fragmented market.
Its February 2026 agreement with Correos Express lets members add parcel services. One commercial agreement opened access to thousands of shops, although each decides whether to take part.
Working through the federation could cut a supplier’s cost of finding retailers and earning their trust. Demonstrations and training could be coordinated across groups of shops, refining the product before wider rollout.
An agreement is only the start. Shops still need to sign up, install the product and keep using it, and the revenue from those that do must cover the cost of winning and supporting them.
Beyond Tickets
The same relationships could also support services that generate income beyond lottery commissions. Parcel collection is one example. In-store advertising is another.
Digital screens could show results and promotions alongside paid advertising, with revenue shared between retailer and supplier. Brands could book campaigns across participating shops through a single platform, and credible audience measurement would help them judge its value.
Advertising could add recurring income alongside software subscriptions or transaction fees, spreading the cost of serving each shop across several services. That depends on advertiser demand, and on revenue covering equipment, maintenance and sales costs while leaving retailers an attractive share.
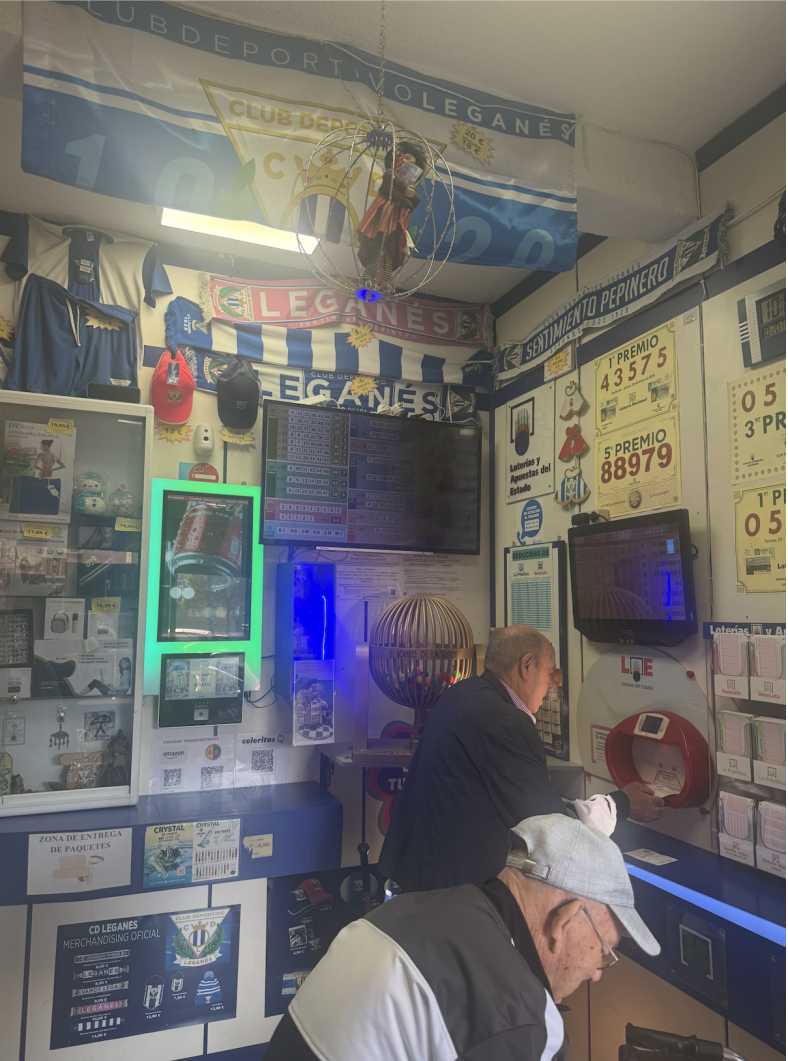
Customers checking tickets at a lottery outlet in Madrid, October 2026.
What We Look For
Our visit reinforced the appeal of serving Spain’s lottery shops, and the need to prove why owners would adopt another product. We would look for measurable extra earnings or time saved, regular use and an economical route into the network, with recurring revenue that stays profitable after installation and support.
Access also needs to last. We would examine federation and retailer agreements, including termination rights and dependence on SELAE’s sales arrangements, and whether customers stay long enough for the supplier to recover its acquisition and installation costs.
For Waterhouse VC, the opportunity is to build on an established habit and a trusted retail network. Suppliers that make each shop more profitable have a reason to be paid year after year. Operators hold the licence. We’d rather clip the ticket.
Pitch Us
If you know any gambling tech companies seeking capital or distribution support, our 'Pitch' page makes it simple to connect with our investment team.
Media
Tom Waterhouse appeared on Ausbiz to talk about Brazil’s provisional shutdown of its regulated online betting market, New Zealand drawing 32 bidders for its online casino licences, and Australia’s legislated ban on online keno and foreign matched lotteries from 1 January 2027.
For wholesale investors interested in following wagering and gaming industry news and trends, please follow our updates on X (@waterhousevc) and WaterhouseVC.com.
DISCLAIMER AND IMPORTANT NOTES
Performance shown is net of fees and expenses and assumes the reinvestment of all distributions on July 1 each year. We make every endeavour to ensure results are accurate. The results are indicative only and subject to subsequent year end external financial review. Past performance is not a reliable indicator of future performance.
Please note the above information in relation to OpenAI, Betfair, Polymarket, Olas (Polystrat), Forkast (ATLAS), Telegram, X, Bill Benter and FanDuel (AceAI) is based on publicly available information and should not be considered nor construed as financial product advice. The information provided in this document is general information only and does not constitute investment or other advice. Readers should consult and rely on professional investment advice specific to their individual circumstances.
Not for Release or Distribution in the United States of America
This material may not be released or distributed in the United States. This material does not constitute an offer to sell, or a solicitation of an offer to buy, any securities in the United States or any other jurisdiction in which such an offer would be illegal. The units in the Fund have not been, and will not be, registered under the U.S. Securities Act of 1933, as amended (the U.S. Securities Act) or the securities laws of any state or other jurisdiction of the United States. Accordingly, the units in the Fund may not be offered or sold in the United States unless they are offered and sold, directly or indirectly, in transactions exempt from, or not subject to, the registration requirements of the U.S. Securities Act and any other applicable United States state securities laws.
General Information Only
This material is for general information only and is not an offer for the purchase or sale of any financial product or service. The material has been prepared for investors who qualify as wholesale clients under sections 761G of the Corporations Act or to any other person who is not required to be given a regulated disclosure document under the Corporations Act. The material is not intended to provide you with financial or tax advice and does not take into account your objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by Sandford Capital, Waterhouse VC or any other person. To the maximum extent possible, Sandford Capital, Waterhouse VC or any other person do not accept any liability for any statement in this material.
Financial Regulatory Oversight and Administration
Waterhouse VC is an Australian Unit Trust denominated in AUD and available to wholesale institutional investors worldwide with a minimum of AUD 500,000 or USD / EUR / GBP / JPY / CHF equivalent. This material has been prepared by Waterhouse VC Pty Ltd (ABN 48 635 494 861) (‘Waterhouse VC’, ‘Trustee’, ‘us’ or ‘we’) as the Trustee of the Waterhouse VC Fund (the ‘Fund’). The Trustee is a corporate authorised representative (CAR 1278656) of Sandford Capital Pty Limited (ABN 82 600 590 887) (AFSL 461981) (Sandford Capital) and appoints Sandford Capital as its AFS licensed intermediary under s911A(2)(b) of the Corporations Act 2001 (Cth) to arrange for the offer to issue, vary or dispose of units in the Fund.
Performance
Past performance of Waterhouse VC is not a reliable indicator of future performance. We make every endeavour to ensure results are accurate. Waterhouse VC Pty Ltd does not guarantee the performance of any strategy or the return of an investor’s capital or any specific rate of return. No allowance has been made for taxation, where applicable. We encourage you to think of investing as a long-term pursuit. Waterhouse VC’s results are indicative only and subject to subsequent year end external financial review.
Copyright
Copyright © Waterhouse VC Pty Ltd ACN 635 494 861. No part of this message, or its content, may be reproduced in any form without the prior consent of Waterhouse VC.
Governing Law
These Terms and Conditions of use are governed by and are to be construed in accordance with the laws of New South Wales. By accepting these Terms and Conditions of use, you agree to the non-exclusive jurisdiction of the courts of New South Wales, Australia in respect of any proceedings concerning these Terms and Conditions of use.