
Waterhouse VC invests globally in publicly listed and private companies across the wagering and gaming ecosystem. The Fund is available to wholesale investors only.
Since inception (August 2019), Waterhouse VC has achieved a net total return of +2,923% (60.5% p.a. annualised) as at 31 October 2026, assuming reinvestment of all distributions on 1 July each year. Past performance is not a reliable indicator of future performance.
Desire Paths
In Florida, a player opens Oink, Oink, Oink on Hard Rock Bet, the casino group’s online app. The reels spin, the pigs line up and the screen flashes a win. It looks like a slot game, but the payout comes from bets on the finishing order of three past NASCAR races.
Florida has never legalised conventional online casinos, but the Seminole Tribe holds the state’s online sports betting monopoly, and its compact with the state includes bets on past motor races. Hard Rock Bet uses those results to deliver a casino-style experience. Demand found another way in.
Anyone who has crossed a park has seen the same thing. When the paved path doesn’t go where people want, they wear a track across the grass. Planners call these desire paths, and they can pave them, fence them off or leave them alone.
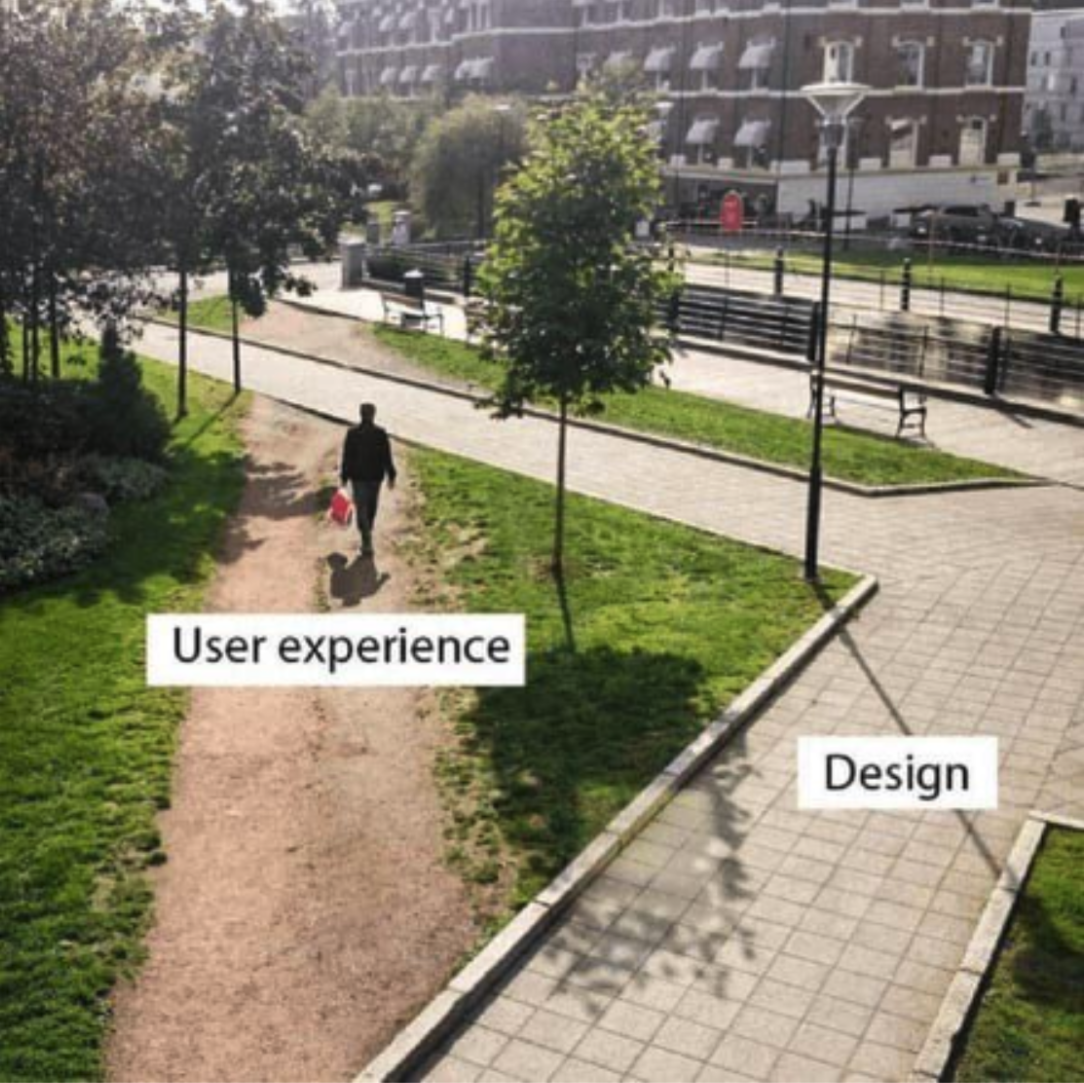
The designed route and the one people use. Source: Natalia Klishina, via 99% Invisible.
America’s online gambling market is criss-crossed with them. What regulators do with each one helps determine who may operate, who owns the customer and who gets paid. The paths also show where demand is heading. For Waterhouse VC, the opportunity lies in technology that serves that demand, whether it brings familiar games to new markets or attracts a different audience altogether.
Unmet Demand
Licensed online casinos operate in only seven US states, and none have launched since Rhode Island in March 2024. Revenue in those markets still rose 27.6% to US$10.73bn in 2025.
Sweepstakes casinos have worn one such path. They sell virtual play coins and give away promotional coins whose winnings can be redeemed for cash. Free entry underpins their argument that these are promotions, not gambling, an interpretation regulators contest.
Perth-founded VGW launched Chumba Casino in 2012, more than a decade before New York’s 2025 crackdown and California’s 2026 ban. That gave it time to build a substantial business, even as access narrowed in individual states.
It paid A$360m in dividends in FY2024, after spending A$418m on marketing. A 2025 founder-led buyout valued its equity at about A$3.2bn. New York’s US$8m settlement with VGW in September 2026 also shows that exiting a market can leave liabilities from past operations.
Licensed competition does not automatically displace these businesses. In Pennsylvania, licensed brands attracted less than half the search interest measured by Blask between January and May 2026, across licensed, sweepstakes and offshore sites. They suggest that sweepstakes and offshore sites continue to attract interest even where players can use licensed online casinos.
Racing Casinos
Florida is not alone. Racing wagers can deliver a casino-style experience where local rules permit both the underlying bet and the way its result is displayed.
Kentucky’s historical land-based horse racing terminals took US$11.2bn in stakes in 2025, with a share funding prize money. Louisiana’s Supreme Court, however, struck down that state’s equivalent law in 2025 for bypassing local voter approval.
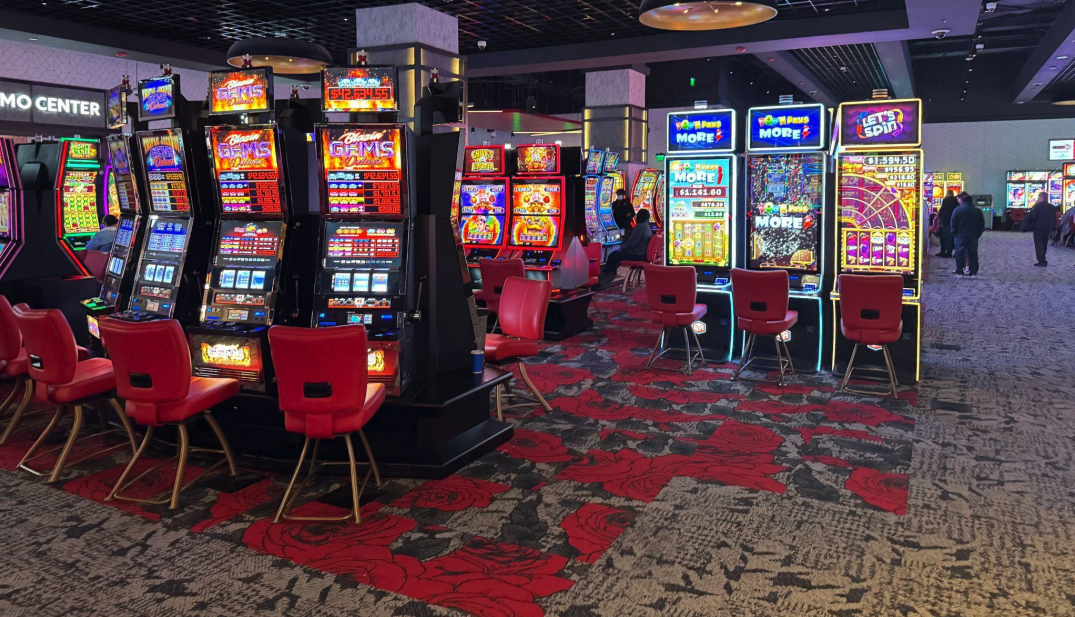
Historical horse racing terminals at The Rose Gaming Resort, Dumfries, Virginia. Photo: Toohool, via Wikimedia Commons, CC BY-SA 4.0
Florida shows the online potential. In October 2026, Eilers & Krejcik Gaming (EKG) estimated Hard Rock’s games based on past motor races were generating about US$2.4bn of annualised gross gaming revenue. For scale, that estimated annual run rate is more than a fifth of the US$10.73bn generated by the seven licensed online casino states in 2025.
Playtech is one of the suppliers, mainly earning a revenue share. Its US and Canadian revenue rose 161% to €56.9m in the first half of 2026, with growth driven chiefly by these games. Hard Rock controls customer access; Playtech earns through that relationship. The owner of customer access may capture much of the value. For suppliers, the question is whether their technology gives them enough bargaining power to retain attractive economics.
For a technology supplier, access to a growing market is the starting point. We favour suppliers whose products are hard to replace and can serve several operators, earning recurring revenue as the market matures.
Game Play Network uses live horse-racing wagers under racing licences. EKG reports that brands using this type of model are live in 22 states. Its patent describes placing bets ahead of time and allocating settled wagers when customers buy credits. The design aims to remove the wait for a race to finish, allowing the immediate results casino players expect.
ASX-listed BetMakers is combining its tote and account platform with games from Bragg and Dreamstreak, whose engine links live horse-race results to slot-style games. The initial focus is US online racing operators, with potential to reach states without licensed online casinos. BetMakers targets a launch in the first quarter of 2027.
New American Playground
Sweepstakes and racing offer a familiar casino experience. A different American opportunity is to bring adult video gamers into real-money play, potentially attracting a new wagering audience.
Paydirt Games, in which Waterhouse VC holds an option, has built cash wagering into a ‘Gold Rush-era’ video game offering players exploration, gold prospecting and character progression.
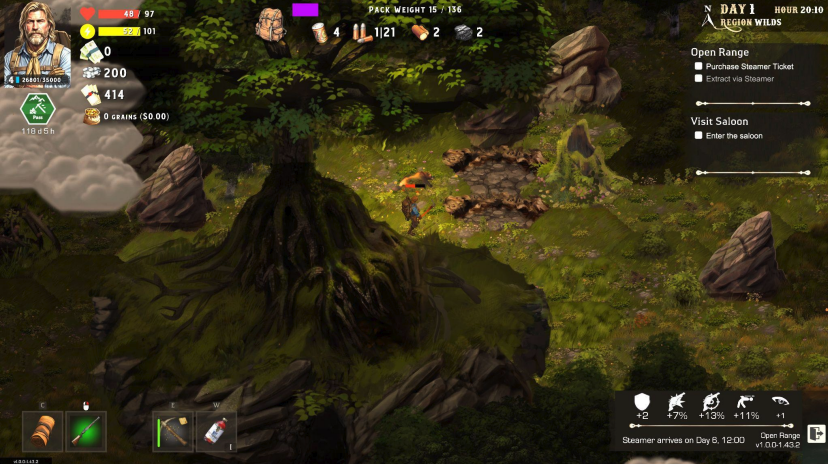
In Fatal Frontier 1869 Gold buried under infinite virtual landscapes of 19th century Alaska can be excavated and redeemed for cash. Source: Paydirt Games.
Players buy time-based subscriptions allowing prospecting for gold and individual mining attempts are effectively pre-purchased cash wagers. Timing, dexterity and other skill-based gameplay aspects influence how much players ultimately cash out.
Paydirt earns mainly from selling players various in-game currencies. These are required to buy picks, shovels, guns and ammo to survive while prospecting with pre-purchased wagers funding all cash rewards.
The company says legal advice supports its single-player wagering model in 45 states. This is not regulatory approval. Paydirt says its model gives it access to mainstream US payment and marketing channels.
Success with its own game could support a wider platform for other game developers: a Steam-like marketplace for real-money games, with shared accounts, identity checks, payments and withdrawals. Game studios could add cash rewards without building those systems themselves. The game must first retain paying players; the platform must then win paying studios.
What We Look For
Our visit reinforced the appeal of serving Spain’s lottery shops, and the need to prove why owners would adopt another product. We would look for measurable extra earnings or time saved, regular use and an economical route into the network, with recurring revenue that stays profitable after installation and support.
Access also needs to last. We would examine federation and retailer agreements, including termination rights and dependence on SELAE’s sales arrangements, and whether customers stay long enough for the supplier to recover its acquisition and installation costs.
For Waterhouse VC, the opportunity is to build on an established habit and a trusted retail network. Suppliers that make each shop more profitable have a reason to be paid year after year. Operators hold the licence. We’d rather clip the ticket.
Pitch Us
If you know any gambling tech companies seeking capital or distribution support, our 'Pitch' page makes it simple to connect with our investment team.
Media
Tom Waterhouse appeared on Ausbiz to talk about Brazil’s provisional shutdown of its regulated online betting market, New Zealand drawing 32 bidders for its online casino licences, and Australia’s legislated ban on online keno and foreign matched lotteries from 1 January 2027.
For wholesale investors interested in following wagering and gaming industry news and trends, please follow our updates on X (@waterhousevc) and WaterhouseVC.com.
DISCLAIMER AND IMPORTANT NOTES
Performance shown is net of fees and expenses and assumes the reinvestment of all distributions on 1 July each year. We make every endeavour to ensure results are accurate. The results are indicative only and subject to subsequent year-end external financial review. Past performance is not a reliable indicator of future performance.
Please note the above information in relation to the American Gaming Association, VGW (Chumba Casino), Blask, the Seminole Tribe of Florida (Hard Rock Bet), Playtech, Game Play Network, BetMakers, Bragg Gaming, Dreamstreak, Valve (Steam) and Paydirt Games (Fatal Frontier 1869) is based on publicly available information and should not be considered nor construed as financial product advice. Waterhouse VC holds an option in Paydirt Games and may benefit financially from its success. The information provided in this document is general information only and does not constitute investment or other advice. Readers should consult and rely on professional investment advice specific to their individual circumstances.
Not for Release or Distribution in the United States of America
This material may not be released or distributed in the United States. This material does not constitute an offer to sell, or a solicitation of an offer to buy, any securities in the United States or any other jurisdiction in which such an offer would be illegal. The units in the Fund have not been, and will not be, registered under the U.S. Securities Act of 1933, as amended (the U.S. Securities Act) or the securities laws of any state or other jurisdiction of the United States. Accordingly, the units in the Fund may not be offered or sold in the United States unless they are offered and sold, directly or indirectly, in transactions exempt from, or not subject to, the registration requirements of the U.S. Securities Act and any other applicable United States state securities laws.
General Information Only
This material is for general information only and is not an offer for the purchase or sale of any financial product or service. The material has been prepared for investors who qualify as wholesale clients under sections 761G of the Corporations Act or to any other person who is not required to be given a regulated disclosure document under the Corporations Act. The material is not intended to provide you with financial or tax advice and does not take into account your objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by Sandford Capital, Waterhouse VC or any other person. To the maximum extent possible, Sandford Capital, Waterhouse VC or any other person do not accept any liability for any statement in this material.
Financial Regulatory Oversight and Administration
Waterhouse VC is an Australian Unit Trust denominated in AUD and available to wholesale institutional investors worldwide with a minimum of AUD 500,000 or USD / EUR / GBP / JPY / CHF equivalent. This material has been prepared by Waterhouse VC Pty Ltd (ABN 48 635 494 861) (‘Waterhouse VC’, ‘Trustee’, ‘us’ or ‘we’) as the Trustee of the Waterhouse VC Fund (the ‘Fund’). The Trustee is a corporate authorised representative (CAR 1278656) of Sandford Capital Pty Limited (ABN 82 600 590 887) (AFSL 461981) (Sandford Capital) and appoints Sandford Capital as its AFS licensed intermediary under s911A(2)(b) of the Corporations Act 2001 (Cth) to arrange for the offer to issue, vary or dispose of units in the Fund.
Performance
Past performance of Waterhouse VC is not a reliable indicator of future performance. We make every endeavour to ensure results are accurate. Waterhouse VC Pty Ltd does not guarantee the performance of any strategy or the return of an investor’s capital or any specific rate of return. No allowance has been made for taxation, where applicable. We encourage you to think of investing as a long-term pursuit. Waterhouse VC’s results are indicative only and subject to subsequent year end external financial review.
Copyright
Copyright © Waterhouse VC Pty Ltd ACN 635 494 861. No part of this message, or its content, may be reproduced in any form without the prior consent of Waterhouse VC.
Governing Law
These Terms and Conditions of use are governed by and are to be construed in accordance with the laws of New South Wales. By accepting these Terms and Conditions of use, you agree to the non-exclusive jurisdiction of the courts of New South Wales, Australia in respect of any proceedings concerning these Terms and Conditions of use.